Safeguard Your Business with Public Liability Insurance
Protect your hard work from unforeseen accidents. Get your Public Liability cover and fast Certificate of Currency (CoC) with Lesure today.
Need an Urgent Certificate of Currency (CoC) Today? We prioritize worksite inductions, commercial leases, and tender deadlines with prompt same-day turnaround in most cases once cover is confirmed.
The Reality of Running a Business
Out on the job, accidents happen. If a mishap causes injury or property damage to a third party (anyone other than employees), you can be held legally liable. Without proper backing, Australian legal fees and compensation claims can be financially crippling. Public Liability insurance acts as your ultimate financial safety net so you can trade with confidence.
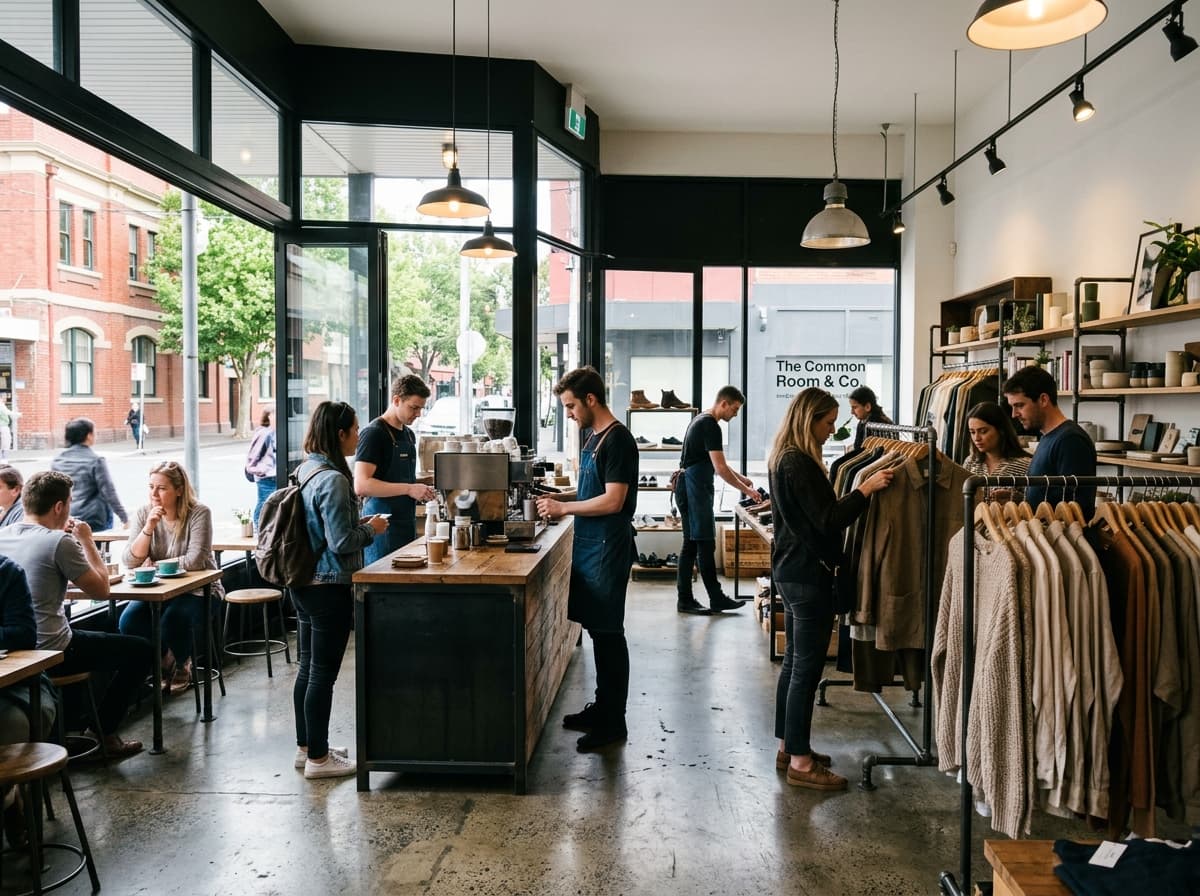
Minimizing everyday slips, trips, and operational mishaps across busy Australian venues.
What is Public Liability Insurance?
Public Liability protects your business from the financial fallout of accidental third-party personal injury or property damage caused by your operations. In Australia, a single minor oversight—whether visiting a client's home or working on a busy construction site—can trigger thousands in claims. This policy steps in to absorb those legal liabilities and protect your livelihood.
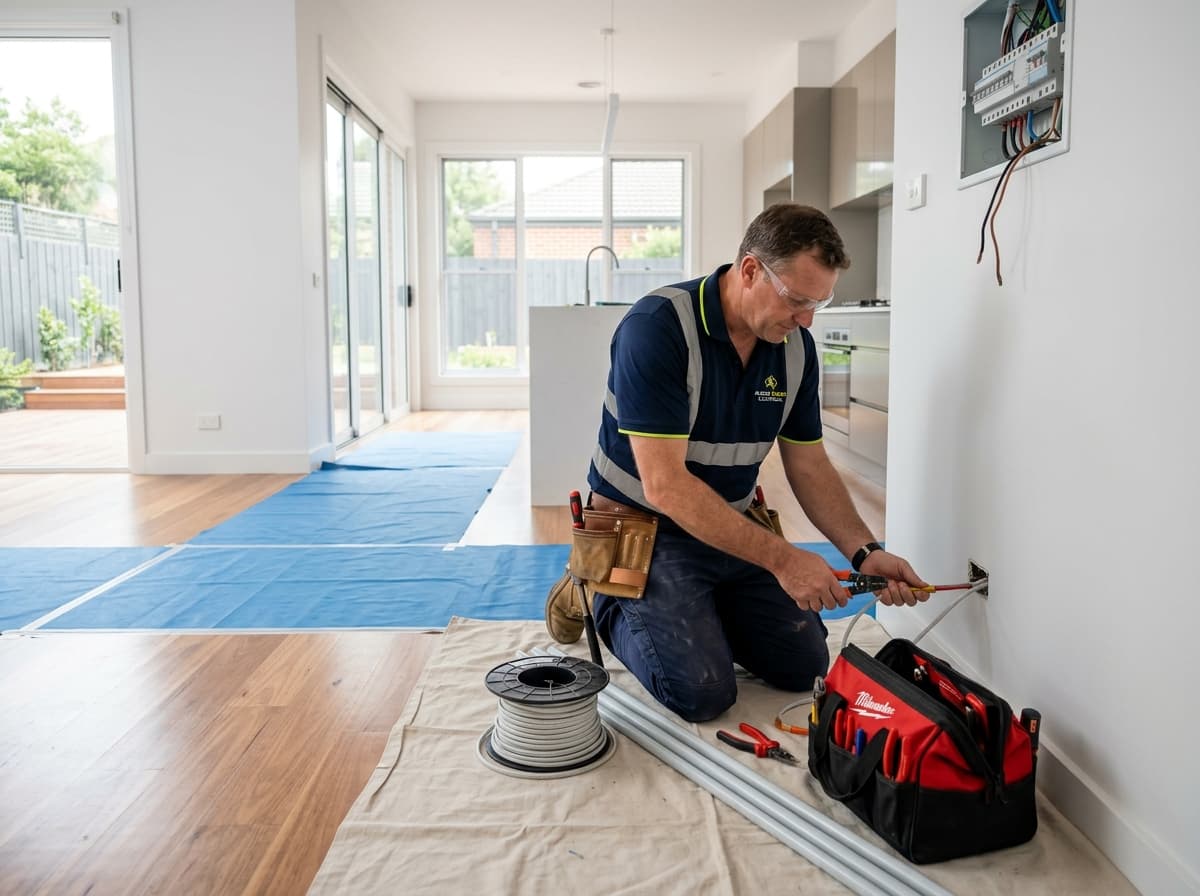
Absorbing third-party personal injury and property damage liabilities with tailored limits.
Coverage Limits
How to Choose Your Public Liability Insurance Limit
Public Liability insurance in Australia is generally structured around three standard tiers of cover. Finding the right fit depends on your specific trade and contract requirements:
| Tier | Best Suited For |
|---|---|
| $5 Million | Small home-based businesses, boutique retail shops, and independent mobile consultants. |
| $10 Million | Standard SME benchmark: local cafes, busy offices, and residential/domestic tradies. |
| $20 Million | Often required for major commercial contractors, subbies on commercial sites, shopping centres, and government projects. |
Coverage Scope
How Public Liability Insurance Has Your Back
Designed to help reduce gaps in your cover and support your business continuity.
Comprehensive Protection Features
Third-Party Personal Injury
Medical bills, rehabilitation, or emotional distress if a client slips on your floor or trips over equipment.
Third-Party Property Damage
Repair and replacement costs if you accidentally damage a client's or neighbouring property.
Legal & Defence Costs
Solicitor fees, investigation expenses, and court payouts—even if the claim made against you is groundless.
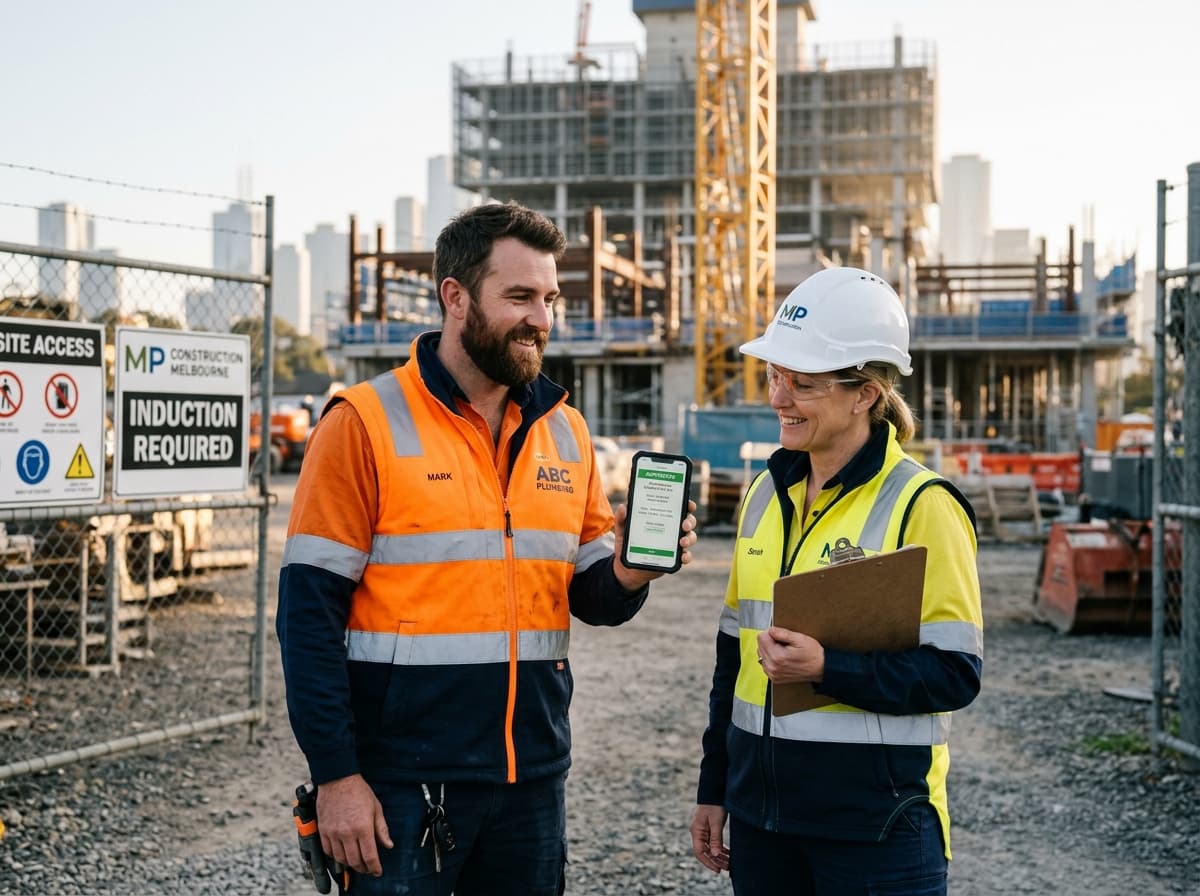
Unlocking commercial job sites, tenders, and leases with mandatory Certificate of Currency compliance.
100% Policy Transparency
What Isn't Covered? (Policy Exclusions)
Every policy has exclusions and limits. Your Lesure broker will walk you through the key ones in your PDS before you buy, so you know where you stand.
Standard Policy Exclusions & Boundaries
Circumstances typically requiring separate extensions or policies
- Staff Injuries: Covered strictly under mandatory Workers’ Compensation, not Public Liability.
- Own Property & Tools: Excludes damage or theft of your own gear, vehicles, or premises.
- Bad Advice or Faulty Designs: Financial loss from poor professional advice requires Professional Indemnity Insurance.
This is why having a broker helps. We walk you through the key policy limits and exclusions in the PDS so you understand your cover before you buy.
Target Audience
Who Should Consider This Cover?
While not legally mandated for all businesses, a valid Certificate of Currency (CoC) is practically compulsory to enter job sites or sign commercial leases. Essential for:
Tradies & Subcontractors: Electricians, plumbers, chippies, and painters—who routinely need a $20M CoC as a non-negotiable requirement for site entry.
Retail & Hospitality Owners: Cafes, diners, boutique shops, and salons where a steady stream of patrons walks through the doors daily.
Mobile Service Providers: Commercial cleaners, gardeners, and consultants who frequently operate on their clients' own property.
The Lesure Advantage
Why We're Different
Broker advice backed by the Steadfast network and decades of underwriting experience.
Steadfast Network Leverage
Access Steadfast policy wordings and compare options from 140+ insurers.
Bespoke, Tailored Precision
Purpose-built policies designed around your specific trade, contracts, and actual business risk profile.
Fast Claims Support
End-to-end claims advocacy. When an incident occurs, we handle the entire process while you focus on your business.
Transparency & Bilingual Support
Clear policy reviews in English or Vietnamese, with the key terms and exclusions explained before you buy.
Common Inquiries
Frequently Asked Questions
Protect Your Hard Work. Trade with Confidence.
Don't let a minor slip up disrupt your business momentum. Let the team at Lesure review your risk profile, secure your competitive premium, and get your Certificate of Currency sorted today.